


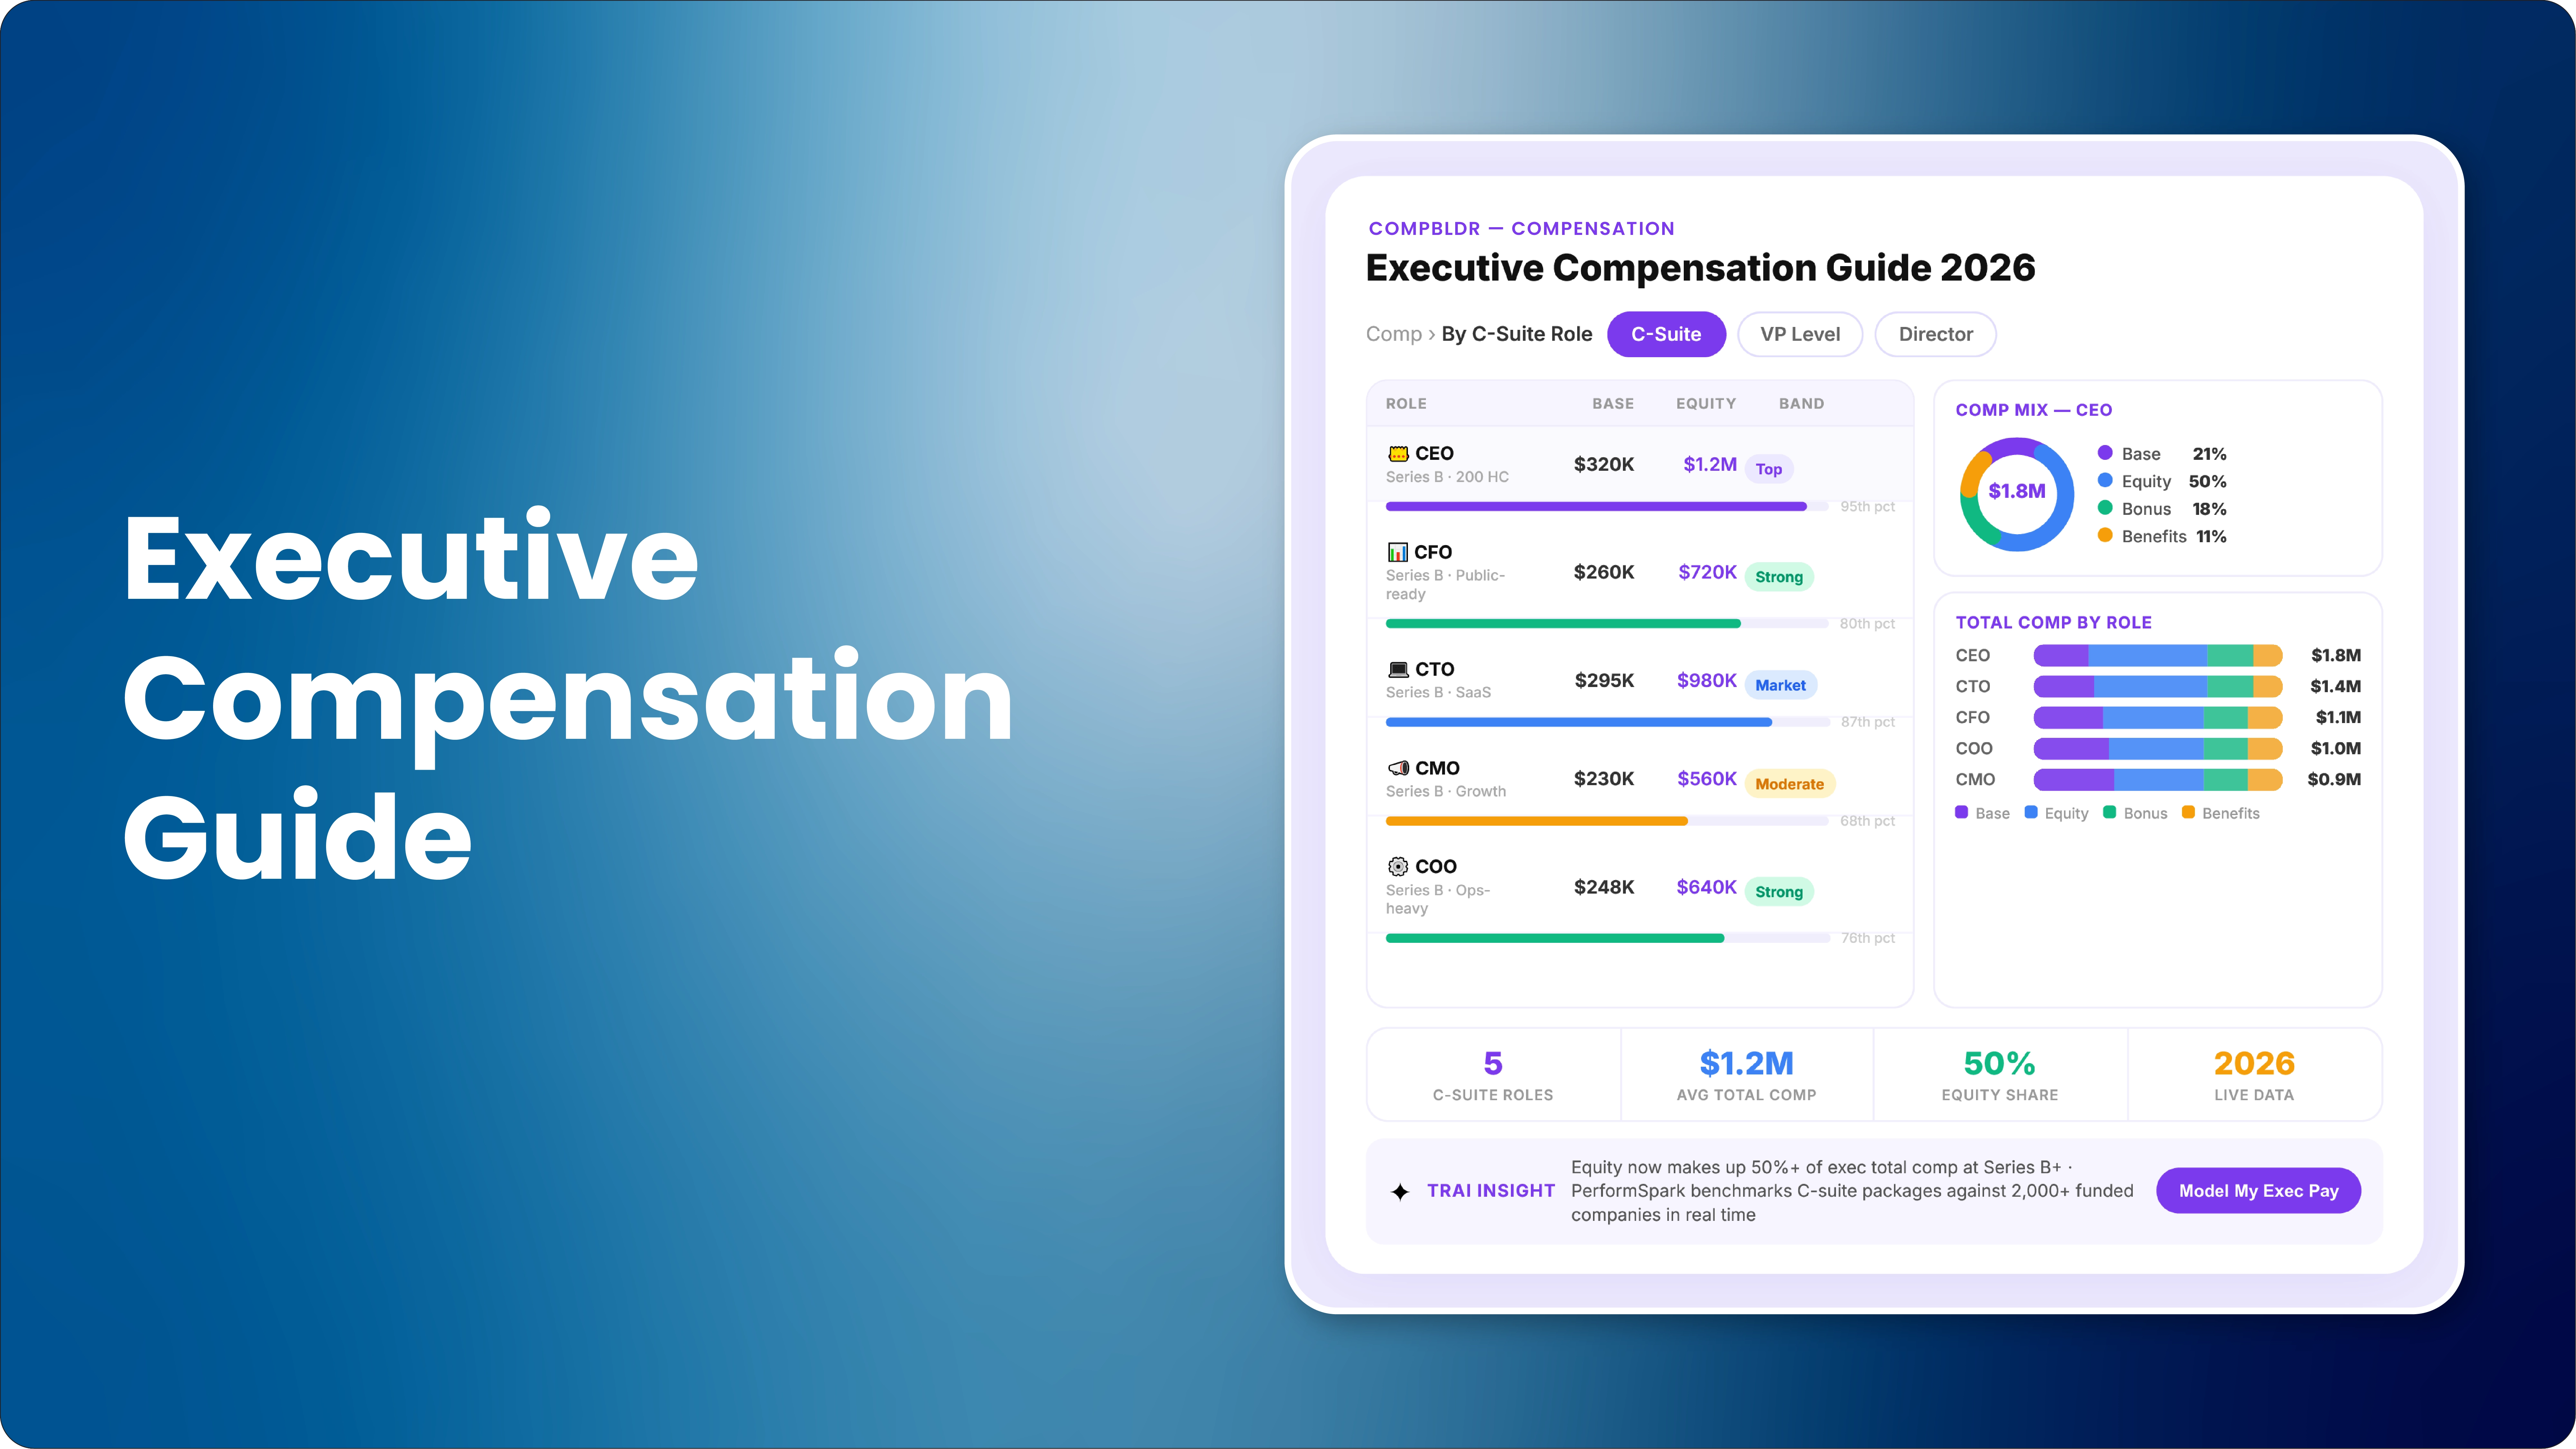

Executive compensation is the combination of fixed pay, annual incentives, long-term incentives, equity or deferred awards, benefits, and other arrangements used to compensate senior leaders. The mix varies materially by organization type, ownership, executive role, business strategy, and governance model. There is no universal percentage of base salary or market percentile that every executive package should target.
At the executive level, the important questions are not only “how much?” They are what role is being compensated, what outcomes the package is designed to support, what market evidence is relevant, what risks the incentives create, who has authority to approve the package, and what record supports the decision.
Review notice: This article provides general compensation-governance information, not legal, tax, securities, accounting, fiduciary, or investment advice. Executive pay requirements differ for public, private, tax-exempt, and other organizations. Use qualified advisers for the applicable rules.
What Is Executive Compensation?
Executive compensation is the total reward arrangement for senior leaders such as CEOs, CFOs, COOs, business-unit presidents, and other executives whose decisions carry material organizational scope. Depending on the organization, the package may include:
- Base salary: fixed cash compensation for the role.
- Short-term incentive: an annual or other short-duration performance-based award.
- Long-term incentive: equity, cash, or other multi-year awards tied to retention, performance, value creation, or a combination.
- Deferred compensation or retirement arrangements: where applicable.
- Benefits and perquisites: only where the organization provides them and subject to applicable tax and disclosure treatment.
- Severance or change-in-control arrangements: where approved in employment or plan terms.
The package should be evaluated as a whole. A lower base salary does not automatically mean lower total compensation, and a large grant-date equity value does not necessarily equal the value ultimately realized by the executive.
Executive Compensation vs. Broad-Based Employee Pay
Broad-based compensation and executive compensation share core disciplines such as job scope, market data, internal relationships, pay philosophy, budgeting, and approvals. Executive programs usually add more complexity because the organization may be balancing enterprise performance, ownership, equity dilution, succession, retention, investor or donor scrutiny, contract terms, and board-level governance.
That does not mean every executive decision is made by a board compensation committee. Governance depends on the organization. Public companies often have board-level processes for named executive officers; private-company authority depends on ownership and governing documents; tax-exempt organizations have their own reasonableness and conflict-of-interest considerations.
The Main Components of Executive Compensation
Base salary
Base salary is fixed cash compensation for the executive role. It may be informed by executive surveys, public-company disclosure data where relevant, recruiter or talent-market information, internal relationships, and the organization's compensation philosophy. The market reference should reflect actual role scope rather than title alone.
Short-term incentives
A short-term incentive, or STI, usually links an award opportunity to annual or other near-term performance. Measures can include financial, operational, strategic, customer, safety, people, or individual objectives depending on the role and business model.
A sound STI design defines the measure, performance period, threshold/target/maximum mechanics where used, weighting, treatment of unusual events, approval authority, and whether discretion can adjust the formulaic result.
Long-term incentives and equity
Long-term incentives, or LTIs, are intended to connect executive rewards with multi-year value, performance, retention, or ownership objectives. Their value should be considered alongside the broader total rewards picture rather than in isolation. Depending on the organization, vehicles can include restricted stock or units, performance awards, stock options, cash-based long-term plans, or other arrangements.
Each vehicle creates different accounting, tax, dilution, vesting, performance, and retention consequences. The compensation team should not treat grant-date value, realized value, and “compensation actually paid” measures as interchangeable.
Benefits, deferred compensation, severance, and other arrangements
Executive packages may include retirement or deferred-compensation arrangements, benefits, perquisites, severance, or change-in-control terms. These items should be reviewed as part of the full package and routed to the appropriate tax, legal, accounting, and governance reviewers.
How to Structure an Executive Compensation Package
1. Define the executive role before pricing it
Document reporting relationship, enterprise or business-unit scope, financial responsibility, geographic footprint, team scale, decision authority, regulatory exposure, transformation mandate, and succession responsibility. A CEO, divisional president, and functional executive can carry very different scope even at similar organization sizes.
Keep the approved role connected to the job description and job architecture where the organization uses them.
2. Decide what the package is supposed to accomplish
Clarify which objectives the organization is trying to support: competitive hiring, retention, annual operating performance, long-term value creation, succession, turnaround, IPO readiness, integration, or another defined outcome. Different objectives can justify different pay mixes and performance horizons. The approved compensation philosophy should explain the principles behind those choices rather than leaving them implicit.
3. Establish relevant market references
Use executive compensation surveys, disclosed public-company data, or other appropriate sources that fit the role and organization. Keep compensation benchmarking and market pricing distinct so the external reference is not mistaken for the final pay decision. Define peer selection before looking at which peers pay more. Review scale, ownership, industry, complexity, geography, and talent market.
The dedicated executive compensation benchmarking guide covers peer groups, role matching, data sources, component-level analysis, and approval records.
4. Design pay mix and performance mechanics
Decide which portion of the opportunity is fixed, short-term performance-based, long-term, equity-linked, deferred, or otherwise contingent. There is no universal “correct” pay-mix percentage. The mix should reflect role influence, ownership model, business maturity, risk, performance horizon, talent market, and compensation philosophy.
5. Model outcomes before approval
Model at least the intended target outcome and the material downside/upside scenarios created by the plan. For incentive designs, test whether the formula could create an unintended payout when one metric improves at the expense of another. For equity, review dilution, vesting, performance conditions, and value sensitivity as appropriate.
6. Review internal relationships
Compare the proposed package with adjacent executives, likely successors, senior vice presidents, and other positions with related enterprise scope. Internal relationships do not require fixed ratios, but they can reveal compression, unexplained inconsistencies, or succession problems that deserve review.
7. Approve and document the decision
Preserve the role scope, market evidence, alternatives considered, performance design, financial impact, conflicts, discretion, reviewers, final decision, and effective date. A governed compensation governance record should explain the judgment, not just the final number.
Worked Example: Why One Headline Benchmark Is Not Enough
Illustrative example: a private company is hiring a new CFO before a planned capital raise. The role owns finance, treasury, tax, investor readiness, and enterprise planning. A survey provides several CFO market references, but some respondents are much smaller companies and others are public multinational organizations.
The compensation team does not average every number together. It applies the same disciplined market-pricing methodology used elsewhere, with additional executive-role and governance context. It identifies the references that most closely match the company's scale and role scope, reviews internal executive relationships, decides how much of the opportunity should be fixed versus performance-based, models the long-term award under different outcomes, and records why the final package differs from the median reference.
The market data informs the decision; it does not make the decision.
Executive Compensation Governance by Organization Type
Public companies
U.S. public-company executive-compensation disclosure is governed in part by Item 402 of Regulation S-K. Current SEC guidance covers areas including Compensation Discussion and Analysis, Summary Compensation Table reporting, pay-ratio disclosure, and pay-versus-performance disclosure. The accounting and disclosure definitions used in those rules do not necessarily equal cash received or value realized by an executive.
SEC: Regulation S-K interpretations, including Item 402.
Securities counsel and other qualified advisers should determine the disclosure treatment for the specific company and arrangement.
Private companies
Private-company governance depends on ownership, board authority, investor agreements, financing arrangements, employment contracts, tax rules, and internal policy. A compensation committee may be used, but it is not a universal requirement for every private company.
Tax-exempt organizations
For applicable tax-exempt organizations, the IRS describes reasonable compensation as the value that would ordinarily be paid for like services by like enterprises under like circumstances. The IRS rebuttable-presumption process generally requires advance approval by an authorized body without conflicts of interest, reliance on appropriate comparability data, and adequate, timely documentation.
IRS: Rebuttable presumption for intermediate sanctions.
The dedicated nonprofit compensation management page covers CompBldr's related workflow context.
What the CEO Pay Ratio Rule Actually Does
Item 402(u) of Regulation S-K requires covered registrants to disclose the ratio of the principal executive officer's annual total compensation to the median employee's annual total compensation. SEC guidance provides flexibility in identifying the median employee, including reasonable estimates, statistical sampling, and other reasonable methods depending on facts and circumstances.
That is more nuanced than simply sorting every employee by one pay field and selecting the middle row. The company must apply the applicable SEC methodology and disclosures.
SEC guidance on calculation of pay-ratio disclosure.
Common Executive Compensation Failure Points
- Pricing the title instead of the role. Executive titles are unusually inconsistent across organizations.
- Selecting peers after seeing their pay. Define peer criteria before using the group as market evidence.
- Copying a “typical” pay mix. The appropriate mix depends on strategy, ownership, role influence, risk, and time horizon.
- Using one percentile as automatic policy. P50 or P75 is a reference point, not an approval rule.
- Mixing compensation measures. Target pay, actual payout, grant-date value, realized value, and regulatory “compensation actually paid” measures can mean different things.
- Ignoring downside behavior. Test how incentive metrics interact under weak, strong, or unusual business outcomes.
- Losing the approval rationale. Preserve why the package was approved, not only the amount.
How CompBldr Supports Executive Compensation Governance
CompBldr can connect executive job records with market benchmarking, compensation planning, approval workflows, analytics, and reporting. That supports a reviewable record from market evidence through recommendation and approval.
Software does not replace board judgment, legal review, tax advice, accounting treatment, or fiduciary responsibility. It helps keep the compensation evidence and internal decision record connected.
Executive Compensation: The Practical Framework
A strong executive compensation process follows this sequence:
role scope → compensation objectives → market evidence → pay mix and performance design → scenario modeling → internal review → approval and documentation.
The package should be explainable in those terms even when the final amount differs materially from a simple market median. Where outside expertise is needed, compensation consulting services can support methodology and analysis while the authorized governance body retains the decision.
Book a Demo to see how CompBldr connects executive job evidence, market references, planning, approvals, and reporting.